
Retirement planning is entering a new era as longer life expectancies, rising healthcare costs and changing employment patterns force Americans to rethink how much they need to save for their later years.
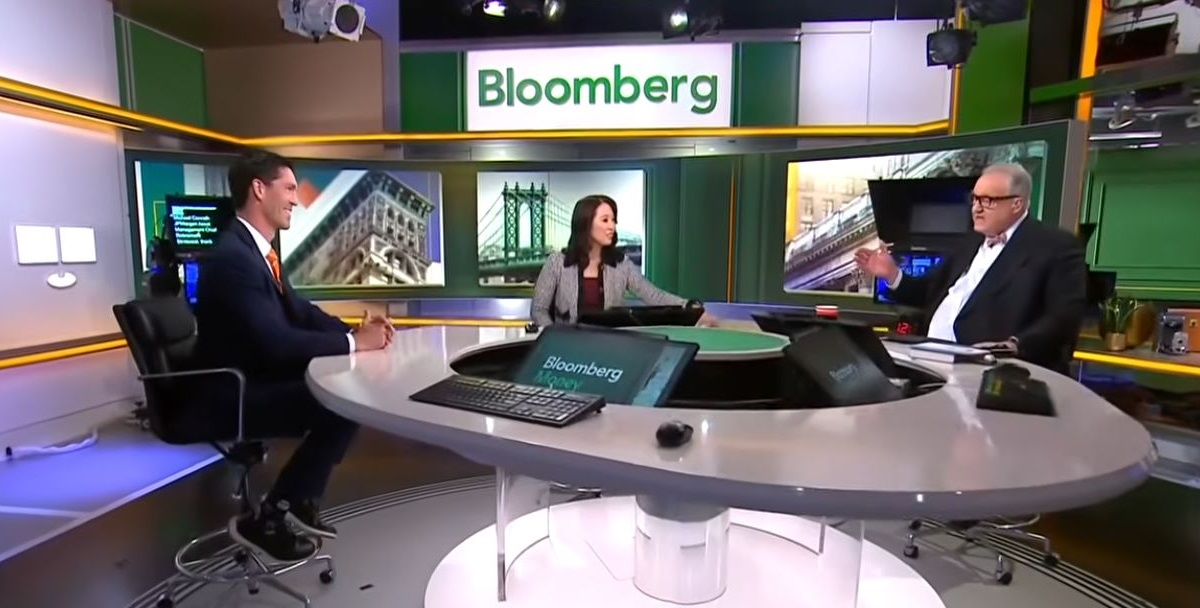
Michael Conrad of JPMorgan Asset Management says retirement savings must increasingly account for the possibility of living well into one’s 90s, making longevity one of the biggest financial challenges facing today’s retirees.
Speaking in a discussion with Bloomberg, Conrad highlighted the growing gap between life expectancy and traditional retirement planning assumptions. According to figures presented during the interview, there is a 74% chance that at least one member of a 65-year-old couple today will live to age 90 or beyond, while the probability rises to 44% for one partner reaching 95.
The figures underline a critical question for retirement planning: How long will your money need to last?
Conrad’s answer is straightforward: retirement savings must last as long as the individual does.
Knowing Your Retirement Number
One of the biggest challenges facing Americans is that many do not know how much money they need to retire comfortably.
Conrad explained that JPMorgan’s retirement guidance uses two basic factors an individual’s age and income to establish savings checkpoints and help people understand whether they are on track.
The goal is to make retirement planning more accessible by giving individuals a practical savings target rather than overwhelming them with complicated calculations.
He also cautioned against allowing short-term economic uncertainty, inflation and changing interest rates to derail long-term financial planning.
Rising Healthcare Costs Add to Retirement Pressure
Longevity is not the only concern. Healthcare expenses are another major financial risk for retirees.
Conrad pointed out that Medicare costs have been increasing at approximately 6% annually, creating additional pressure on retirement budgets.
As people live longer, they may need to finance healthcare and everyday expenses for several decades after leaving full-time employment. This makes it increasingly important to account for healthcare inflation alongside investment returns and general living costs.
Starting Late Does Not Mean It Is Too Late
The conversation also addressed younger generations who are struggling to achieve traditional financial milestones, including homeownership, starting families and building retirement savings.
For people who begin saving in their 40s, Conrad emphasized that it is never too late to get started.
He encouraged workers to get invested, remain invested and avoid trying to time the market. He also highlighted employer-sponsored retirement plans and company matching contributions as valuable opportunities that workers should take advantage of.
For employees with access to a 401(k), securing the full available employer match can provide an important boost to long-term savings.
Homeownership and the Changing Face of Retirement
Retirement is no longer necessarily a sudden transition from full-time employment to complete withdrawal from the workforce.
Conrad noted a growing trend toward partial retirement, where individuals continue working until they pay off their mortgages before transitioning into full retirement.
Using anonymized data available through JPMorgan Chase, the firm examines how households save, spend and borrow to better understand changing financial behaviour.
This highlights how homeownership, mortgage repayments and retirement planning are increasingly interconnected.
Small Businesses and Independent Workers Need Better Retirement Options
Conrad also highlighted the retirement savings challenges facing small-business owners and self-employed workers.
Unlike salaried employees, small-business owners often reinvest profits into their businesses while postponing personal financial planning.
He pointed to the SECURE 2.0 legislation, which provides tax incentives to encourage eligible small businesses to establish retirement plans.
Automatic enrolment and contribution increases can also help employees build retirement savings over time.
For independent workers, freelancers and influencers, Individual Retirement Accounts (IRAs) remain an important option, even when traditional employer-sponsored retirement plans are unavailable.
Don’t Count on Double-Digit Investment Returns
Another important takeaway from the discussion concerned investment return expectations.
With markets having delivered strong returns in recent years, investors may become accustomed to expecting double-digit annual gains.
Conrad cautioned against building retirement plans around recent market performance.
JPMorgan’s projections are based on long-term capital market assumptions rather than short-term market rallies. He referenced a balanced portfolio return assumption of around 7%, with the possibility of an additional 0.5 percentage points from alternative investments, depending on allocation.
The message is clear: retirement plans should be built around realistic long-term expectations rather than assuming that recent market performance will continue indefinitely.
The Bottom Line
As life expectancy increases, retirement planning is becoming more complex. Longer retirements, healthcare inflation, mortgage obligations and uncertain investment returns all require individuals to rethink their financial goals.
Conrad’s central message is that people should start planning early, remain invested, take advantage of available employer contributions and regularly review their retirement savings targets.
If 90 is becoming the new retirement planning benchmark, the challenge is no longer simply accumulating enough money to stop working at 65. It is building a financial strategy capable of supporting a longer and potentially more expensive life.